Ghana is drafting its 2027 budget with a fresh promise: turn years of debt restructuring and spending restraint into tangible jobs, investment and higher output. The challenge is that the repayments due in 2027 will compete for the same public money that the government seeks to deploy for development.
The International Monetary Fund finished its final review of Ghana’s US$3 billion Extended Credit Facility in July, and its successor, the Policy Coordination Instrument, will now provide monitoring without new financing. The budget must therefore demonstrate how Ghana intends to sustain its recovery while paying for its next phase of development.
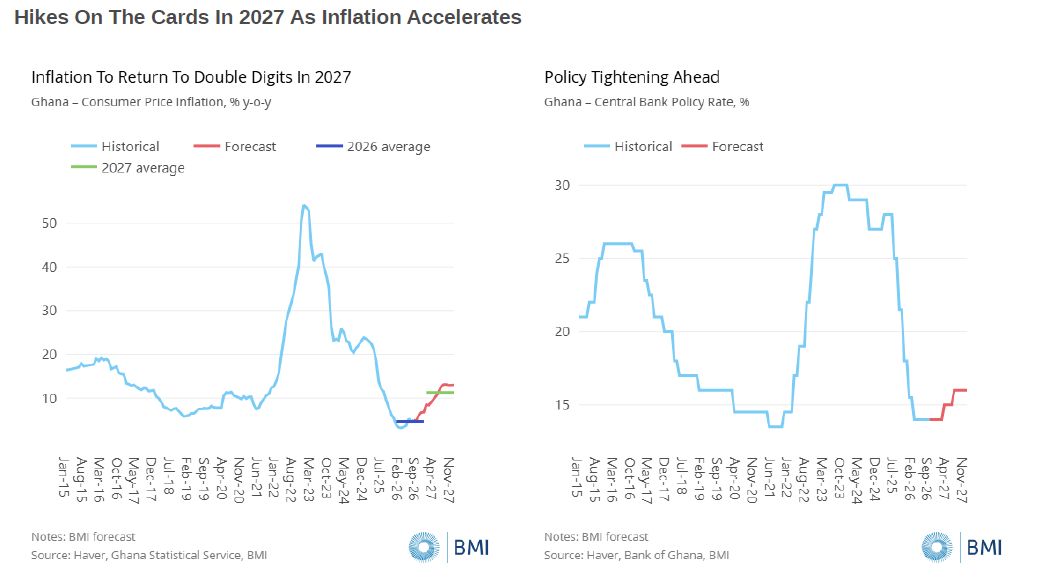
September inflation stood at 5.2 % and provisional public debt was 45 % of GDP in June, but those figures alone cannot show whether new investments will deliver or how comfortably the government can meet its repayments. The budget must be judged on how convincingly it links its promises to financing and results. Five tests have emerged as critical.
The Fiscal Strategy Document proposes an investment equivalent to 1.5 % of GDP annually for four years – roughly US$10 billion – funded by an additional 0.5 % of GDP in revenue and by room created through a reduction of the primary surplus. The budget must now detail what the money will be used for, which projects are ready to begin, who will implement them and when results can be expected. A programme intended to create jobs needs measurable employment and production targets alongside its costs, and any private investment expected to follow should be distinguished from money the government has actually committed, with public guarantees disclosed.
The government plans to lower the primary surplus on a commitment basis from 1.5 % to 0.5 % of GDP from 2027. Reducing the surplus leaves more room for expenditure but also means a smaller contribution towards containing debt, all else being equal. Productive projects can justify greater investment, but the harder task is selecting those projects and protecting the budget if expected revenue fails to arrive. The government should explain how the proposed target fits the applicable fiscal rules, what safeguards accompany it, and which spending would be reconsidered if conditions deteriorate. Independent scrutiny by the Fiscal Council would help establish confidence in those choices.
Repayment demands are steep. The government has announced GH¢58 billion of Domestic Debt Exchange Programme bond maturities in 2027 and another GH¢53 billion in 2028. A sinking fund is therefore reasonable. Government reported GH¢15.6 billion accumulated by 22 July, while the Institute for Fiscal Studies questioned its treatment in the approved budget. The next budget should reconcile the fund’s opening balance, inflows, withdrawals and planned repayments, distinguishing money saved from money borrowed to build a buffer. Borrowing ahead of maturity can ease immediate pressure, but it brings interest costs and another repayment date.
Preparing for repayments must also leave room to deliver today’s budget. The Ministry of Finance reports a first‑half primary surplus of 0.9 % of GDP on a commitment basis. Yet capital spending was 39.3 % below plan, while net arrears clearance reached only 38.2 % of the programmed amount. The improved balance deserves recognition; the shortfalls deserve explanation. Delayed payment of old arrears does not itself explain a commitment‑basis surplus. Nevertheless, unfinished projects and overdue bills have consequences beyond the fiscal tables. Contractors waiting for payment may struggle to pay suppliers and workers, and communities waiting for infrastructure continue to bear the cost of its absence. Government should show what it committed to spend, what it paid and what remains overdue. Where spending fell below plan, the explanation should distinguish genuine savings, rejected claims and delays in delivery. Spending less is not automatically evidence of failure, nor is it sufficient evidence of efficiency.
Even a well‑executed budget can be disrupted by obligations elsewhere in the public sector. The Fiscal Strategy Document already includes a Fiscal Risk Statement. The budget should build on it by showing how much major exposures could cost taxpayers, when support might be required and who is responsible. Energy‑sector obligations, guarantees, gold‑purchase operations and central‑bank recapitalisation need clear treatment. The IMF’s July review recorded a waiver linked to cost‑sharing under the domestic gold purchase programme and reaffirmed the commitment to recapitalise the Bank of Ghana by 2032. These issues need an explanation of their cost and financing. Liabilities already included in public debt should be distinguished from claims that might become government obligations, so that disclosure neither hides exposures nor counts them twice.
The 2028 election‑year budget will be presented in late 2027. The coming budget is therefore an opportunity to establish safeguards before political spending pressures intensify. Its credibility will depend on what happens after the speech: whether projects progress, payments arrive and emerging risks are reported promptly.
None of these asks for less ambition. It asks government to cost its promises, explain its fiscal choices, prepare for repayments and account for delivery. Ghana’s next phase of development needs a budget that connects ambition to evidence and survives an audit.