GCB Bank announced that its operating income for the first nine months of 2026 rose 32.4 % year‑on‑year to GH¢5.70 billion, while profit before tax increased 42.6 % to GH¢2.87 billion and profit after tax climbed 44.0 % to GH¢1.86 billion. Earnings per share lifted to GH¢9.38 from GH¢6.51 a year earlier.
Interest income grew only 1.3 % to GH¢4.39 billion, reflecting the pressure from lower market rates, but interest expense fell nearly a third to GH¢816 million, allowing net interest income to rise 14.0 % to GH¢3.57 billion. The real driver of the earnings lift was non‑funded income: net fee and commission income surged 87.4 % to GH¢1.07 billion, and trading income jumped 71.6 % to over GH¢1.0 billion. Together, non‑funded income now accounts for about 37 % of operating income, up from roughly 27 % a year earlier.
Operating efficiency improved, with the cost‑to‑income ratio falling to 45.1 % from 49.2 % a year earlier. The balance sheet expanded strongly: customer deposits grew 22.8 % to GH¢50.88 billion, while net loans and advances rose 57.3 % to GH¢25.23 billion. Investment securities increased 21.1 % to GH¢19.80 billion, and total assets expanded 29.0 % to GH¢67.62 billion.
GCB’s loan growth outpaced the industry, with net loans rising 57.3 % versus a sector average of 16.4 % year‑to‑August. The non‑performing loan ratio fell to 4.8 % from 10.8 % a year earlier, below the industry ratio of 15.7 % in August.
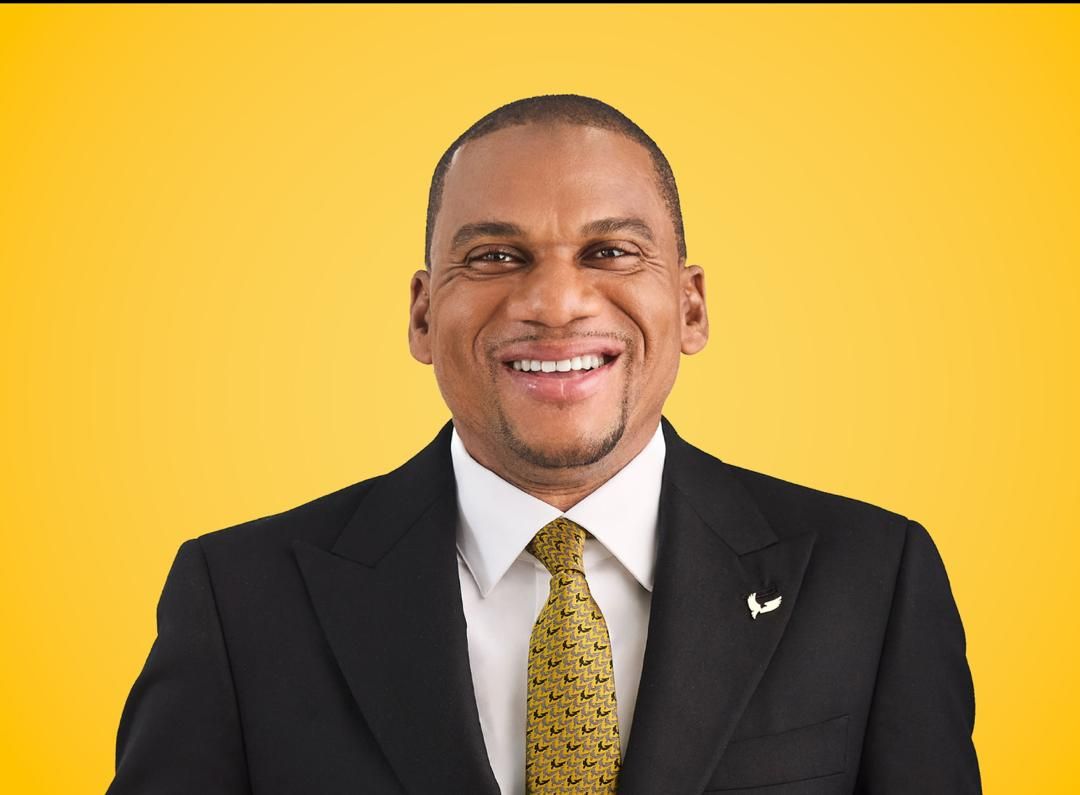
Managing Director Farihan Alhassan said the lower‑rate environment forces banks to return to commercial banking fundamentals, and that GCB is focused on building a resilient loan portfolio that can perform through cycles while supporting Ghana’s next phase of growth. He added that the bank remains committed to delivering stronger customer value and solutions for businesses, households and the wider economy.
However, the expansion has consumed balance‑sheet capacity: impairment charges rose to GH¢260 million, capital adequacy eased to 14.6 % from 16.2 %, and the liquidity ratio declined to 64.3 % from 73.4 %. While none of these figures signal distress, they underscore the need for disciplined underwriting and balance‑sheet management as the bank continues to grow credit and non‑funded income.
Looking ahead, lower rates and resilient domestic activity should support credit demand and transaction volumes, but the bank must maintain capital and liquidity control while sustaining its broader earnings mix.