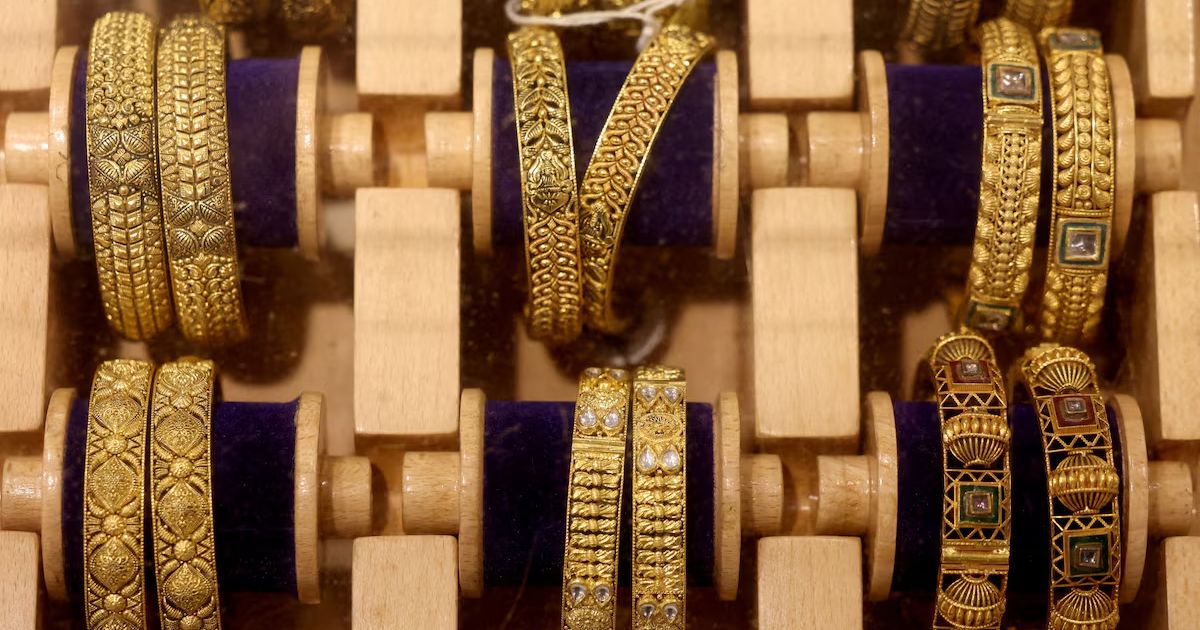
Spot gold rose more than 1% on Monday, climbing 1.6% to $4,129.69 per ounce by 0220 GMT, as softer oil prices eased inflation concerns and a weaker U.S. dollar made bullion more affordable for overseas buyers. U.S. gold futures for December delivery mirrored the gain, rising 1.6% to $4,139.00.
Oil prices fell after President Donald Trump said he was highly unlikely to order further attacks on Iran, as talks to end the conflict continued. The decline in crude helped reduce expectations that interest rates would stay higher for longer, lowering the opportunity cost of holding non‑yielding bullion.
"Trump's more conciliatory tone toward Iran is helping keep a lid on oil prices, which in turn eases some of the inflation pressure that had been weighing on the metal along with a modest pullback in the dollar," said Tim Waterer, chief market analyst at KCM Trade.
Meanwhile, U.S. job growth accelerated in October and the unemployment rate fell to 4.1%, reinforcing expectations that the labour market remains resilient and keeping the Federal Reserve on track for a December interest‑rate increase. Traders now see a 79% chance that the Fed will raise rates in December, up from 71% prior to the payrolls data, according to CME's FedWatch tool.
Market participants are awaiting the U.S. Consumer Price Index data due on Tuesday and the Producer Price Index on Friday to further gauge the Fed's monetary policy stance. "Any hot readings would likely firm the dollar and lift the odds of a December rate hike, which would quickly put gold back on the defensive," Waterer added.
Among other metals, spot silver climbed 2.8% to $53.31 per ounce, platinum gained 1.6% to $1,556.14 and palladium rose 2.1% to $1,044.28.